Every producer of a tradable commodity arrives, sooner or later, at the same temptation. Acting alone, a seller is a price-taker, disciplined by competitors who will undercut any attempt to hold output back. Acting together, the same sellers can become price-makers, withholding supply to lift the price of what remains. The arithmetic is seductive and ancient: restrict the quantity, harvest the margin. Yet the history of commodity coordination is overwhelmingly a history of failure. For every cartel that has bent a market for decades, a dozen have splintered within a few selling seasons. Understanding why most collapse, and why the survivors survive, is less a story about greed than about structure, geology, and the unsentimental mathematics of who can afford to defect.
The temptation and the trap
A cartel is, at its core, a mechanism for solving a coordination problem in the producers’ favour and at the customer’s expense. If a handful of suppliers agree to cap production, the market price rises above the competitive level and each member earns more on every unit sold. The difficulty is that the same elevated price that rewards the group also rewards the cheat. Any single member can quietly expand output, selling extra barrels or tonnes into a market propped up by everyone else’s restraint, and capture an outsized gain before the others react.
This is the cartel’s permanent internal contradiction. The agreement is most profitable precisely when it is most fragile, because the incentive to defect grows with the price the cartel achieves. Economists describe the stable arrangement as one where the long-run value of continued cooperation exceeds the one-off windfall of cheating. In practice that condition is rarely met for long. Members differ in their costs, their reserves, their time horizons, and their political need for revenue, and those differences are what tear the structure apart.
Why most cartels die young
The decisive variable is the spread of marginal costs across members. When one producer can pump or mine far more cheaply than the others, that producer eventually concludes it is better off abandoning restraint and seizing volume. The global potash market made the logic explicit. For years roughly 70 percent of world supply moved through two marketing alliances, North America’s Canpotex and the Belarusian Potash Company, which paired Russia’s Uralkali with Belarus’s Belaruskali. In 2013 Uralkali, among the lowest-cost producers in the industry, walked away from its alliance to chase market share rather than price. The structure dissolved almost overnight; the announced price guidance fell from around $400 a tonne toward under $300, and the combined stock-market value of the listed Canpotex owners dropped by nearly $12 billion in a single trading session. The low-cost member had run the numbers and decided that scale, not collusion, was its advantage.
The same fault line runs through oil. In 2020 the loose alliance known as OPEC+ briefly shattered when Russia refused Saudi demands for deeper cuts and Riyadh responded by flooding the market with discounted crude. Brent, which had been trading above $70 a barrel, collapsed toward $20, and the price of one US futures contract famously turned negative for a single day. The war lasted barely a month before both sides, staring at fiscal ruin, reassembled the agreement with cuts on the order of ten million barrels a day. The episode was a textbook demonstration of the discipline problem: even the most powerful coordinators will defect when they conclude a rival is free-riding on their restraint, and the punishment phase is mutual and brutal.
Beyond cost dispersion, three further forces shorten a cartel’s life. New entrants, drawn by the high price, erode the founders’ share until coordination becomes meaningless. Substitution lets buyers escape: aluminium for copper, synthetic alternatives for natural inputs, efficiency for raw volume. And in most developed jurisdictions the law treats explicit price-fixing as a serious offence, so any agreement written down or spoken on a recorded line is a liability waiting to detonate.
Explicit versus tacit coordination
The legal exposure forces a crucial distinction. Explicit cartels, where firms meet, agree on prices, and allocate customers, are illegal across the United States, the European Union, and most major economies, and the penalties are severe enough to be existential. The lysine conspiracy of the 1990s ended with Archer Daniels Midland pleading guilty in 1996 and paying a combined $100 million, comprising a $70 million fine for the lysine count and a further $30 million for citric acid, with executives jailed and the case immortalised in the phrase prosecutors lifted from the conspirators themselves: the customer is the enemy. The contemporaneous vitamins cartel produced a $500 million penalty against Hoffmann-La Roche in 1999, then the largest criminal antitrust fine the US Justice Department had ever obtained, with a separate $225 million fine for the German co-conspirator BASF. These are not market-bending success stories; they are cautionary tales of detection.
Tacit coordination is a subtler and more durable creature. Here no agreement is ever made. Firms in a concentrated industry simply observe one another, recognise their mutual interest in restraint, and converge on parallel behaviour without communicating. A market with few players, transparent prices, similar cost structures, and high barriers to entry can sustain supra-competitive prices indefinitely without a single incriminating meeting. Antitrust law struggles to reach this conduct because parallel pricing alone is not a conspiracy; proving the meeting of minds requires evidence that, by design, does not exist. The most effective coordination, in other words, is frequently the kind that never names itself.
The diamond exception
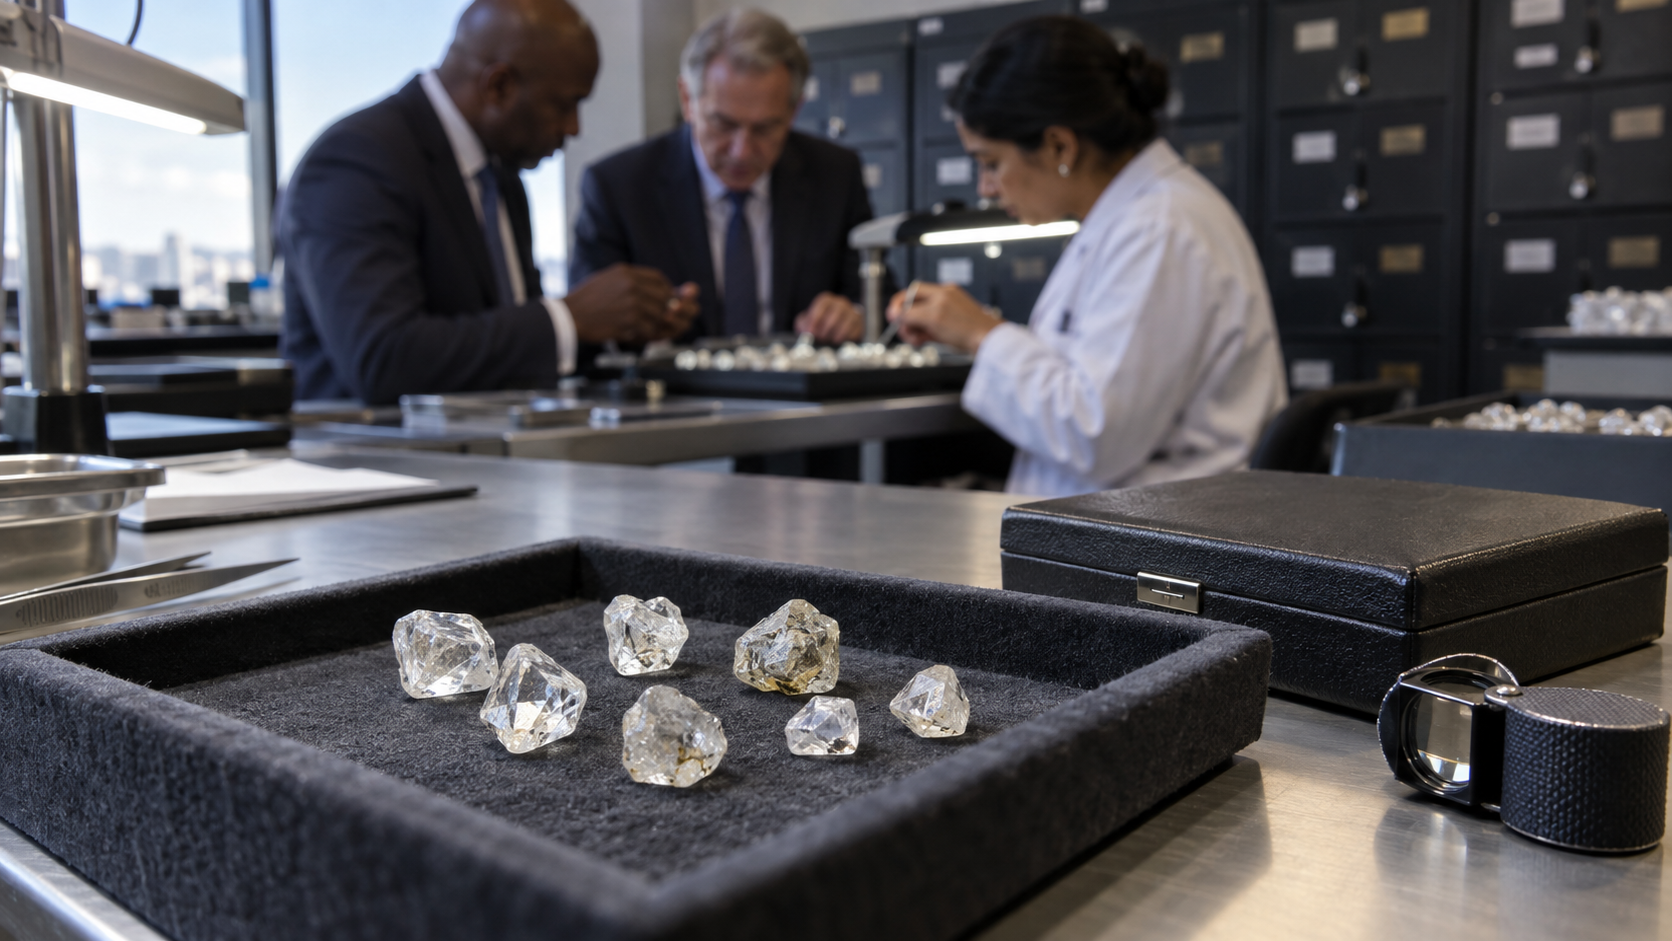
If most cartels are studies in decay, De Beers was for a century the great exception, and it is worth understanding why. From its consolidation under Cecil Rhodes, the company controlled the overwhelming majority of rough diamond distribution, a share that ran as high as 90 percent for much of the twentieth century. Its method was not merely to mine but to control the channel. Through the Central Selling Organisation, De Beers bought up production it did not own, stockpiled stones to manage scarcity, and rationed supply to a closed circle of buyers who took what they were offered or lost their place.
What made the arrangement endure was a rare alignment of structural advantages: physical control of the world’s richest deposits, a willingness to hold vast and costly inventory across cycles, and a marketing achievement of singular power. The campaign that fixed the phrase “A Diamond Is Forever” in the public mind, coined for De Beers in 1947 by the agency N.W. Ayer, manufactured the very demand the cartel existed to ration, while simultaneously discouraging resale that might have flooded the market with second-hand stones. De Beers did not just restrict supply; it engineered the belief that a diamond was a possession one never sold, neutralising the secondary market that undermines most commodity schemes.
Even this fortress eroded. New discoveries and independent sellers in Russia, Australia, and Canada brought production De Beers could not absorb, and its share of the rough market fell from its peak toward under 30 percent, with Russia’s Alrosa emerging as a comparably sized producer. The lesson is not that durable market power is impossible but that it demands a combination of control over supply, capital deep enough to carry inventory, and an ability to shape demand itself, conditions that almost no commodity producer can replicate.
What the survivors share
The enduring cases share a recognisable profile. Supply is concentrated in few hands and protected by geology or capital from rapid entry. A dominant member is willing and able to act as the swing producer, cutting its own output to defend the price and absorbing the cost of policing the others. OPEC functions, to the degree it functions, because the bloc collectively sits on close to 80 percent of the world’s proven crude reserves, and because Saudi Arabia has historically played the swing role, holding the spare capacity to punish defectors by opening the taps. Where no member will shoulder that burden, the structure cannot hold.
The shipping conferences offer the counter-example of a coordination regime killed not by its own arithmetic but by the law. For more than a century, liner conferences openly fixed freight rates on ocean routes under formal exemptions from competition rules. The European Union withdrew that block exemption in 2008, ending lawful rate-setting on its trades and forcing carriers into looser operational alliances that may share vessels but not prices. A cartel that survives only because it is legally privileged ends the moment the privilege is revoked.
The strategic implication
The cartel instinct is constant; its success is conditional. Coordination bends a market only where supply is genuinely scarce and concentrated, where a credible swing producer will pay to enforce discipline, where buyers cannot easily substitute away, and where the arrangement either operates within the law or never leaves a fingerprint. Strip away any one of those conditions and the structure reverts to the competitive equilibrium it was built to escape, usually with a price collapse that punishes its architects. For analysts, the durable signal is not the announcement of a production agreement, which is cheap and frequent, but the underlying geometry of cost and control beneath it. The cartels worth watching are the ones that never have to call themselves cartels, because the structure does the coordinating for them.
Report Disclaimer
This report is provided for informational purposes only and does not constitute financial, legal, or investment advice. The views expressed are those of Bretalon Ltd and are based on information believed to be reliable at the time of publication. Past performance is not indicative of future results. Recipients should conduct their own due diligence before making any decisions based on this material. For full terms, see our Report Disclaimer.